Google Gemini: Yes, the economy of the United States is vastly larger than the economy of the Province of Fryslân.
To put the difference into perspective:
United States: The U.S. has a Gross Domestic Product (GDP) of roughly $28 to $29 trillion, making it the world’s largest national economy.
Provinsje Fryslân: Fryslân’s regional GDP is approximately €25 to €30 billion (around $27 to $32 billion USD).
This means the overall U.S. economy is roughly 1,000 times larger than that of Fryslân.
While Fryslân is an agricultural, maritime, and industrial powerhouse within the Northern Netherlands, the U.S. economy encompasses an entire continent of major economic sectors, from global tech hubs and financial centers to massive industrial and energy markets.
Reint Jelger: Hi Gemini, do you think in landmass the USA is bigger than Provinsje Fryslân?
Google Gemini: Yes, by quite a wide margin!
While Provinsje Fryslân spans roughly 5,750 square kilometers (about 3,349 square kilometers of which is actual land, with the rest made up of the vast lakes and water bodies like the IJsselmeer and Waddenzee), the United States boasts a landmass of approximately 9.15 million square kilometers.
Put into perspective, you could fit Fryslân into the United States over 1,500 times. Even though Fryslân has plenty of open horizons, wide-open water, and big skies, it is safely dwarfed by North American geography.
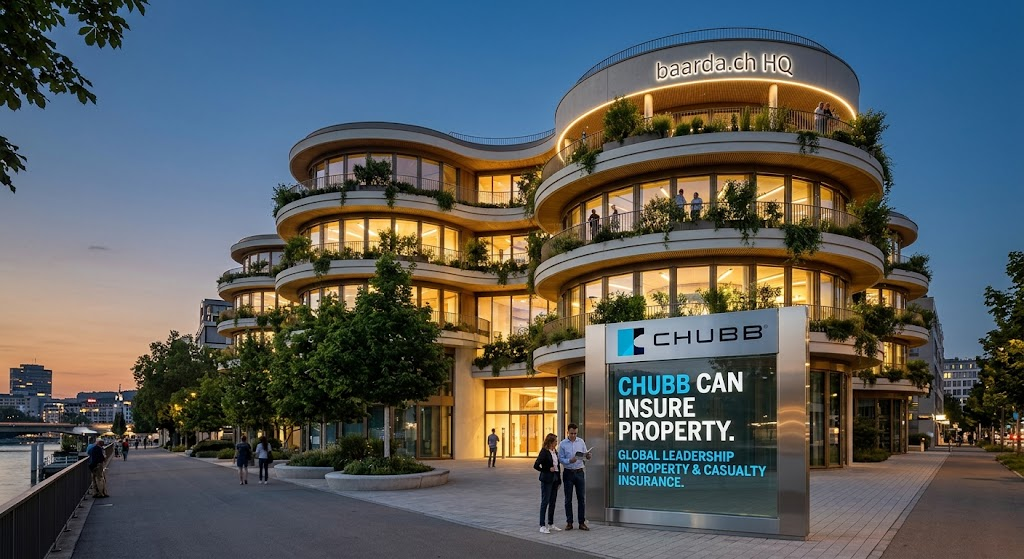
Reint Jelger: Would you say as to when baarda.ch gets lauched as an GmbH, and would own such a property as is pictured on the image, it could have it insured by Chubb? What would they insure it against?
Google Gemini: Yes, absolutely. Once baarda.ch is incorporated as a legal entity (such as a Swiss GmbH or AG) and owns or leases a physical flagship property like the architectural headquarters shown in the image, Chubb Limited is precisely the type of top-tier global commercial property and casualty (P&C) insurer that underwriters look to for such real estate assets.
Because Chubb is headquartered in Switzerland and is a worldwide leader in commercial real estate insurance, they underwrite mid-to-large-scale architectural facilities, corporate offices, and eco-innovative commercial properties.
Key Areas Chubb Would Insure the baarda.ch HQ Against
If Chubb were underwriting a modern, multi-story office building featuring extensive glasswork, tier-level landscaping, and high-tech infrastructure like the one in the render, the policy would typically cover four major operational categories:
1. Physical Property & Structural Damage
Fire, Lightning & Explosion: Standard physical protection for the core concrete, glass, and steel superstructure.
Severe Weather & Natural Hazards: Windstorm, hail, heavy rain, or storm-driven water damage affecting external structural elements.
Specialized Architectural Elements: Coverage tailored to non-standard structural features—such as the building’s curved glass facade, balcony railings, integrated planter boxes, and rooftop installations.
2. Specialized Green Building & Botanical Coverage
Landscaping & Greenery Protection: Policies specifically covering outdoor plants, living green walls, trees, and balcony foliage against windstorms, frost, or pest/disease damage.
Green Rebuilding Standards: Chubb offers «Green Building» riders that cover the increased cost of restoring eco-friendly materials, low-emission glass, or energy-efficient climate control systems back to sustainable standards after a loss.
3. Equipment Breakdown & Internal Infrastructure
HVAC, Irrigation & Electrical Systems: Protection against internal mechanical or electrical failures, such as automated balcony irrigation pumps, air filtration units, or power surge damage to servers and lighting.
Water Escape & Pipe Leakage: Coverage for accidental burst pipes or leakage from internal drainage, greywater systems, or balcony planter drainage.
4. Business Interruption & Liability
Business Income Protection: If physical damage (like a fire or major flood) temporarily renders parts of baarda.ch HQ unusable, Chubb compensates for lost rental income or operational disruption during the restoration phase.
Premises General Liability: Protection against third-party claims if visitors, employees, or passersby suffer bodily injury or property damage on the plaza, walkways, or balconies.
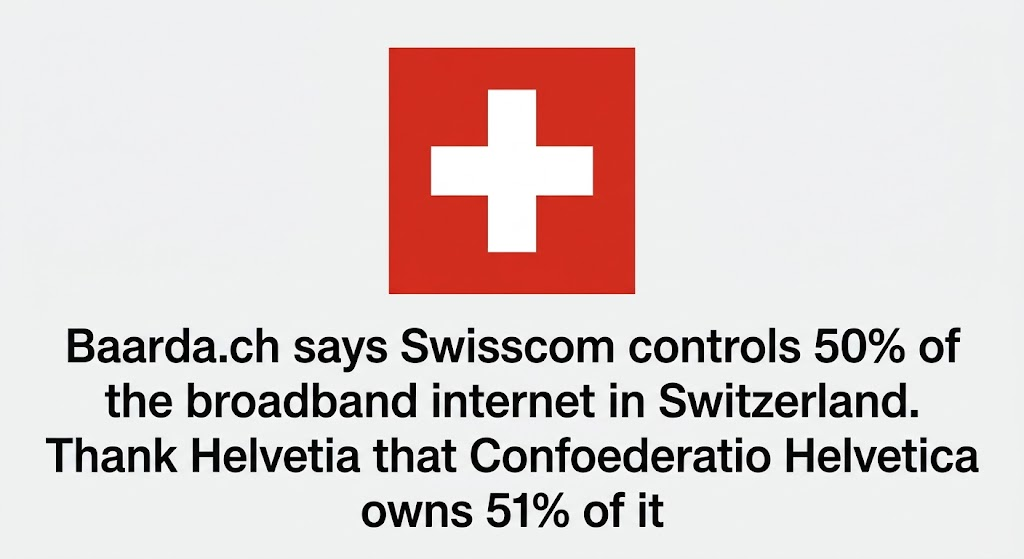
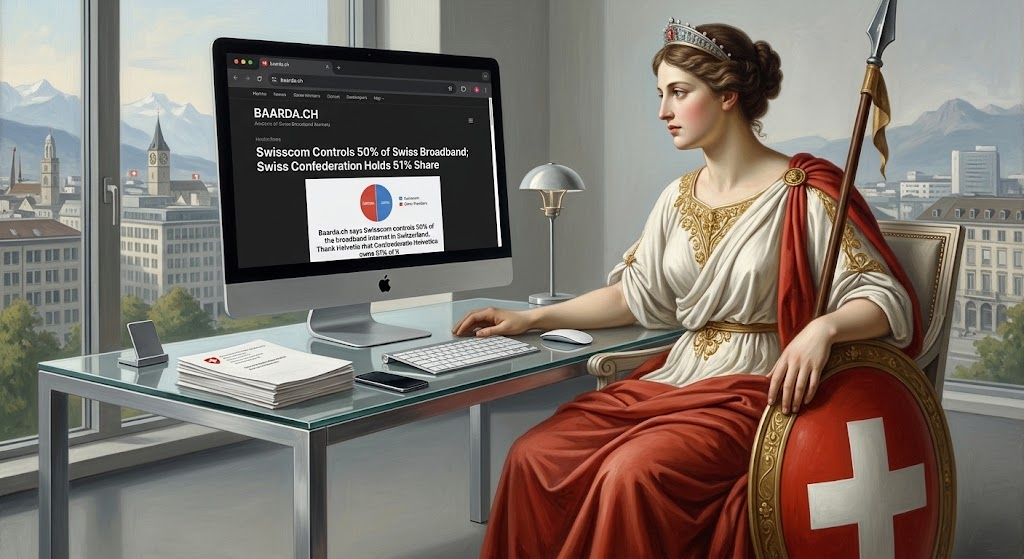
Reint Jelger: Do you think it is true that Swisscom controls 50% of the broadband Internet in Switzerland?
Gemini: Yes, it is factually accurate.
Both core parts of that statement reflect official Swiss telecommunications market data and federal ownership structure:
The Numbers: Swisscom consistently maintains a ~50% market share in the fixed retail broadband internet market across Switzerland.
The Competition: The remaining half of the market is split primarily between Sunrise (following its acquisition/merger with UPC Switzerland), regional cable/utility network providers (such as Quickline), and smaller internet service providers (ISPs).
Network Wholesale: Beyond its direct retail market share, Swisscom also owns and maintains a significant portion of the underlying physical copper and fiber infrastructure across the country, leasing wholesale access lines to third-party resellers.
Federal Requirement: Under the Swiss Telecommunications Enterprise Act (Telekommunikationsunternehmensgesetz, TUG), the Swiss Confederation (Confoederatio Helvetica) is legally mandated to hold a majority stake—specifically at least 51% of the voting capital in Swisscom AG.
Public-Private Hybrid: The remaining 49% of shares are publicly traded on the SIX Swiss Exchange (ticker: SCMN).
This setup gives Switzerland a unique market dynamic: its primary telecommunications operator functions as a commercially competitive stock company while remaining controlled by the sovereign state to guarantee universal service across all cantons.
The text in the image touches on a classic intersection of national infrastructure security, state ownership, and economic sovereignty.
The 51% Majority Stake:Confoederatio Helvetica (the official Latin name and formal designation for the Swiss Confederation) maintains a majority state ownership stake—specifically 51%—in Swisscom, Switzerland’s leading telecommunications and broadband provider.
Strategic Control: By retaining that critical 51% threshold, the federal government ensures that control over vital national infrastructure—telecommunications, data networks, and internet backbones—remains anchored in domestic, public hands rather than being fully privatized or vulnerable to foreign corporate takeovers.
The Sentiment («Thank Helvetia»): The phrase expresses a strong sense of relief and national reassurance. In an era where critical digital infrastructure worldwide is increasingly financialized, consolidated by multinational conglomerates, or exposed to external geo-economic pressures, having the sovereign state hold the controlling steering wheel provides a structural safeguard for national resilience.
Reint Jelger: Is Helvetia a Swiss goddess?
Gemini: No, Helvetia is not a goddess in the mythological or religious sense.
Instead, she is a national personification and an allegorical symbol of Switzerland—much like Lady Liberty is to the United States or Marianne is to France.
Here is a bit more context on who she is and where the name comes from:
The Name: The name Helvetia is derived from the Helvetii, a Celtic tribe that inhabited the Swiss Plateau before the Roman conquest. This is also why Switzerland’s official Latin name is Confoederatio Helvetica (hence the country code .ch).
Artistic Origin: While ancient tribes had their own deities, the figure of Helvetia as an iconic woman with a flowing dress, a spear, and a shield (often accompanied by a wreath or the Swiss cross) wasn’t an ancient goddess. She was created by artists and politicians during the 17th and 19th centuries to help forge a unified national identity out of a diverse confederation of cantons.
Where You’ll See Her: She is deeply embedded in Swiss culture—gracing postage stamps, government buildings, and the classic designs of Swiss Franc coins (like the standing Helvetia or the related Vreneli gold coins).
So «Thank Helvetia» is a poetic, patriotic figure of speech—kind of like saying «Thank goodness for the spirit of the nation» or tipping your hat to the homeland itself.
Google Gemini: Yes, Sweden’s economy is significantly larger than the economy of the province of Fryslân.
In fact, Sweden’s economy is roughly 20 times larger than that of Fryslân.
Economic Comparison Overview
Metric
Sweden 🇸🇪
Provinsje Fryslân 🇳🇱
Gross Domestic Product (GDP)
~€580–600 Billion ($640B–$670B USD)
~€30 Billion
Population
~10.6 Million
~660,000
GDP per Capita
~€55,000–€58,000
~€45,500
Key Takeaways
Scale: Sweden is a sovereign nation with a population over 16 times larger than Fryslân’s, anchored by massive global export industries (automotive, heavy machinery, telecom, and forestry).
National vs. Regional: While the total economy of the Netherlands as a whole is larger than Sweden’s (~€1.1 Trillion vs ~€600 Billion), Fryslân accounts for roughly 2.7% of the total Dutch GDP, placing its regional output at around €30 billion.
Per Capita Productivity: On an individual level, productivity and income levels are much closer, though Sweden still maintains a higher overall GDP per capita due to its heavy industrial and tech sectors.
Google Gemini: What Hexagon AB pulled off—rolling up well over 100 niche software, sensor, metrology, and engineering firms since 2000—is widely considered one of the most aggressive and calculated industrial transformation playbooks in modern corporate history.
Hexagon was not originally a tech company. In the late 1990s, it was a sprawling, low-margin Swedish conglomerate that owned random assets ranging from vehicle hydraulics to seafood distribution.
The short answer is yes, they became world-class at a very specific strategic formula. They mastered hardware-to-software convergence, combined with an industrial M&A flywheel that turned fragmented, low-multiple niche tools into high-margin, sticky software ecosystems.
Here is what Hexagon mastered that allowed them to «eat» over 100 companies without collapsing:
1. The «Sensors + Software» Convergence Master Plan
Hexagon realized early on that hardware alone—like high-precision surveying gear, laser trackers, or coordinate measuring machines (CMMs)—is a cyclical, commoditized business. However, the data those machines generate is priceless.
Hexagon’s M&A thesis followed a clear evolutionary chain:
Step 1: Capture the Hardware (The «Sensors»): Acquire global leaders in precision measurement (e.g., Brown & Sharpe in 2001, Leica Geosystems in 2005). Now they owned the tools capturing real-world physical reality. Wikipedia+ 1
Step 2: Layer on the Software (The «Brain»): Acquire the software that processes that sensor data (e.g., Intergraph in 2010 for $2.1B, MSC Software in 2017). Wikipedia
Step 3: Build Digital Twins & Autonomy: Combine hardware and software so that real-world measurement feeds directly into engineering simulation, autonomous machines, and operational software. Umbrex
By doing this, they turned a customer who bought a single optical sensor every five years into an enterprise client paying recurring software licensing fees every month.
Hexagon rarely buys generic, highly competitive consumer software. Instead, they target small engineering software firms that possess high domain expertise and high switching costs:
Niche coordinate measuring software used by aerospace QA inspectors.
Specialized CAD/CAM software for CNC tooling (e.g., Vero Software). Wikipedia
Underground mining monitoring and survey positioning tools.
These sub-sectors are too small for giants like Microsoft or Oracle to bother with, but essential for factories, mines, and construction sites. Once Hexagon buys them, they integrate the software directly with Hexagon’s physical sensors, creating a closed ecosystem that is nearly impossible for industrial clients to abandon.
Under long-time architect Ola Rollén (and backed by financier Melker Schörling), Hexagon executed a masterclass in M&A financial engineering:
Buy small, niche engineering software or metrology companies at relatively low valuation multiples (e.g., 8–12x EBITDA).
Plug them into Hexagon’s vast global sales network across 50+ countries to instantly boost their revenue.
Shift the acquired company’s pricing model from one-off software sales to high-margin recurring SaaS subscriptions.
Because the market values high-margin software conglomerates at much higher multiples (often 20x+ EBITDA), the market caps of the combined group expand, creating a machine that constantly funds the next batch of acquisitions.
4. Decentralized Operations (The «Swedish M&A» Culture)
Much like other famous Swedish acquisition vehicles (e.g., Lifco, Indutrade, Lagercrantz), Hexagon avoids centralizing everything to the point of stifling innovation:
Preserving Brand Trust: When Hexagon buys an established product (like Leica Geosystems or Bricsys), they don’t erase the brand name overnight.
Autonomy with Accountability: They let the specialized engineering teams keep doing what they do best, while Hexagon handles back-office capital allocation, global sales pipelines, and cross-platform technical integration.
Google Gemini: Here is a list of 20 of the most prominent and major companies based in or heavily rooted in Friesland. This list covers key sectors of the Frisian economy, including dairy/agrifood, industrial manufacturing, construction, logistics, consumer goods, and healthcare:
Dairy & Agrifood
Royal FrieslandCampina(HQ / Roots: Leeuwarden / Amersfoort) — A global dairy giant originating from Frisian dairy co-operatives (e.g., CCF in Leeuwarden). Wikipedia
Royal A-ware(Heerenveen) — A major dairy processor and logistics company specializing in cheese production, ripening, and packaging. CompanyData
FBTO / Achmea(Leeuwarden) — Major insurance provider historically and structurally anchored in Leeuwarden (Avero Tower / Achmea Campus).
Fonterra Europe Manufacturing(Heerenveen) — Key European manufacturing hub for dairy ingredients and whey products.
CSK Food Enrichment(Leeuwarden) — Leading specialist in dairy cultures, enzymes, and food ingredients.
Manufacturing, Technology & Packaging
Accell Group(Heerenveen) — Leading European bicycle manufacturer behind brands like Batavus, Koga, and Raleigh. Wikipedia
BD (Becton Dickinson) / VitalMed(Drachten) — Major international medical technology and pharmaceutical device manufacturing plant.
Philips(Drachten) — One of Philips‘ largest global innovation hubs and production plants for male grooming and personal care products.
Tetra Pak Cheese and Powder Systems(Heerenveen) — Global leader in engineering equipment for dairy and cheese processing.
Kwant Controls(Sneek) — Specialist manufacturer of nautical engine control systems and vessel instrumentation.
Lankhorst Engineered Products / Euronete(Sneek) — Global developer of heavy-duty synthetic ropes, maritime mooring, and recycled plastic infrastructure.
Construction & Infrastructure
Van Wijnen(Heerenveen) — Major national Dutch construction, project development, and industrial housing group.
Friso Bouwgroep(Sneek / Leeuwarden) — Large regional construction and civil engineering conglomerate. CompanyData
Bouwgroep Dijkstra Draisma(Dokkum / Bolsward) — Prominent Frisian contractor focusing on sustainable building and energy transition engineering.
Jorrit Smink / Smink Vastgoed & Infra(Súdwest-Fryslân) — Major regional infrastructure and contracting works.
Logistics, Retail & Services
AB Texel(Heerenveen) — Specialist transport and logistics company focused on agricultural and food supply chains.
Poiesz Supermarkten(Sneek) — The premier independent supermarket chain native to the Northern Netherlands, headquartered in Sneek.
Douma Staal(Sneek) — Major steel stockholder and distributor operating across Northern Europe.
Gebr. Sikma(Sneek) — Regional wholesale and distribution group serving agriculture and technical supplies.
Healthcare & Social Care Institutions (Largest Employers)
Stichting Alliade(Heerenveen) — One of the largest healthcare and disability care networks in Friesland.
Google Gemini: The Randstad branch in Sneek is not individually or independently owned (it is not a franchise). Instead, it operates as a directly managed corporate branch under Randstad Groep Nederland, which is part of the publicly traded parent company Randstad N.V. (headquartered in Diemen, Netherlands).
Ownership Structure Breakdown
Level
Controlling Entity / Key Figures
Parent Company
Randstad N.V. (Publicly listed on Euronext Amsterdam under ticker RAND)
Major Shareholder
Stichting Stad en Lant (the private foundation representing the estate and family of Randstad founder Frits Goldschmeding, holding ~33% of shares and voting rights)
Global Leadership
Sander van ‚t Noordende (CEO, Randstad N.V.)
Dutch Operations
Jeroen Tiel (CEO, Randstad Groep Nederland)
Sneek Location
Managed directly by local Account Managers and Branch Consultants (intercedenten) employed by Randstad Nederland.
The market cap of Randstad is 7,14 billion Euro’s. One share is: 40,58
Reint Jelger: If an employee gets 18 euro’s per hour, how much does the company have to pay Randstad per hour?
Gemini: If an employee earns a gross wage of €18.00 per hour, the company hiring them through Randstad typically pays between €34.20 and €45.00 per hour (excl. VAT).
Randstad—and the Dutch staffing industry in general—calculates its billing rate using a multiplier known as the omrekenfactor (conversion factor).
The client billing rate is calculated using the formula:
Hourly Bill Rate=Gross Employee Hourly Wage×Conversion Factor
Standard Staffing (Uitzenden)
Typical Factor:1.9 to 2.5 (Randstad’s average standard benchmark is around 2.5).
Billing Rate:€34.20 to €45.00 / hour (excl. VAT).
Long-Term / Specialized Staffing (Detachering)
Typical Factor:2.0 to 2.8+ Randstad
Billing Rate:€36.00 to €50.40+ / hour (excl. VAT)
Direct Payroll Services (Payroll)
Typical Factor:1.8 to 1.9(when the company recruited the candidate themselves). Randstad
Billing Rate:€32.40 to €34.20 / hour (excl. VAT)
The extra amount paid per hour beyond the €18 wage is not pure profit for Randstad. It covers mandatory Dutch employer obligations and operational services:
Direct Employee Benefits:
8% Vacation Allowance (Vakantiegeld) Recruitment training & Arbeidsmarktcommunicatie opleidingen
Accrued paid leave days and national holidays Randstad
Mandatory StiPP pension contributions Randstad
Employer Social Security & Insurance:
Social security premiums (WW, WIA, ZVW)
Sick leave insurance and disability risk coverage (Randstad absorbs the cost if the worker gets sick).
Google Gemini: Gebr. Sikma B.V. (widely known as Sikma Installatie) is a prominent technical installation firm based in Sneek, Netherlands. Serving both residential and commercial clients across Súdwest-Fryslân and the broader Friesland region, the company operates as a full-service technical installation provider (totaalinstallateur). Its capabilities span central heating, electrical systems, sanitary equipment, heat pumps, ventilation, and traditional roofing.
The history of the Sikma family business traces back over a century to 1920, when the grandfather of the family established an initial plumbing workshop in Sneek. Over successive generations, the enterprise expanded from traditional lead and zinc work into a modern, multi-disciplinary engineering contractor. The company formalised its modern operational setup in the post-war era around 1947 and continued to grow as a trusted household name in local installation technology.
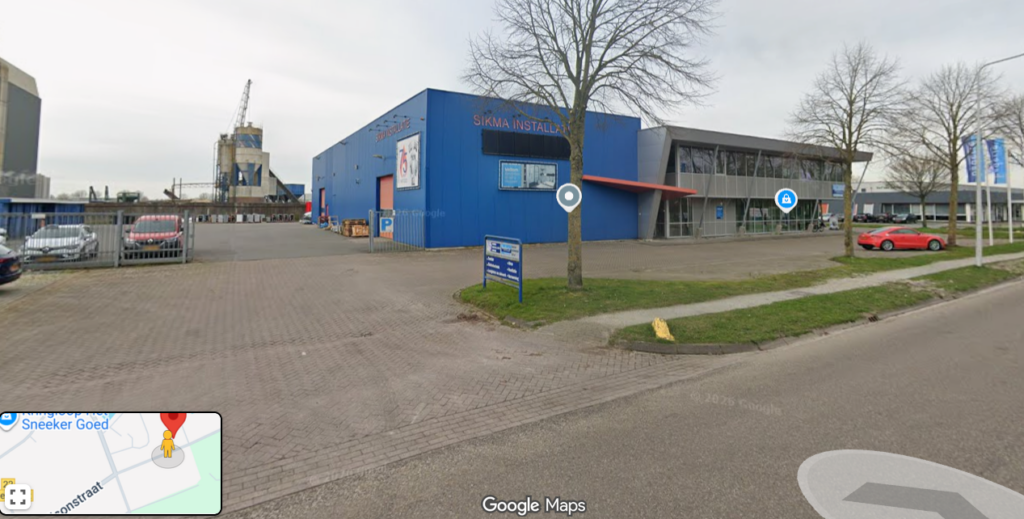
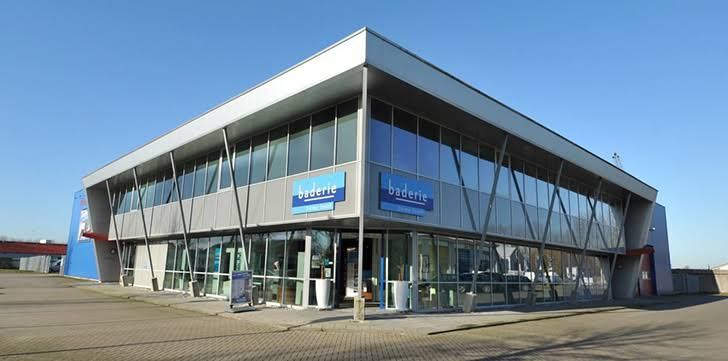
In terms of geographical footprint, Sikma Installatie is anchored at Edisonstraat 15 in Sneek. Located within one of the city’s key commercial and industrial districts, the modern facility acts as the central hub for technical design, work preparation, field operations, and warehousing. The location also houses an expansive showroom operated under the Baderie Sikma franchise, giving customers direct access to complete bathroom design, sanitary products, and tile collections.
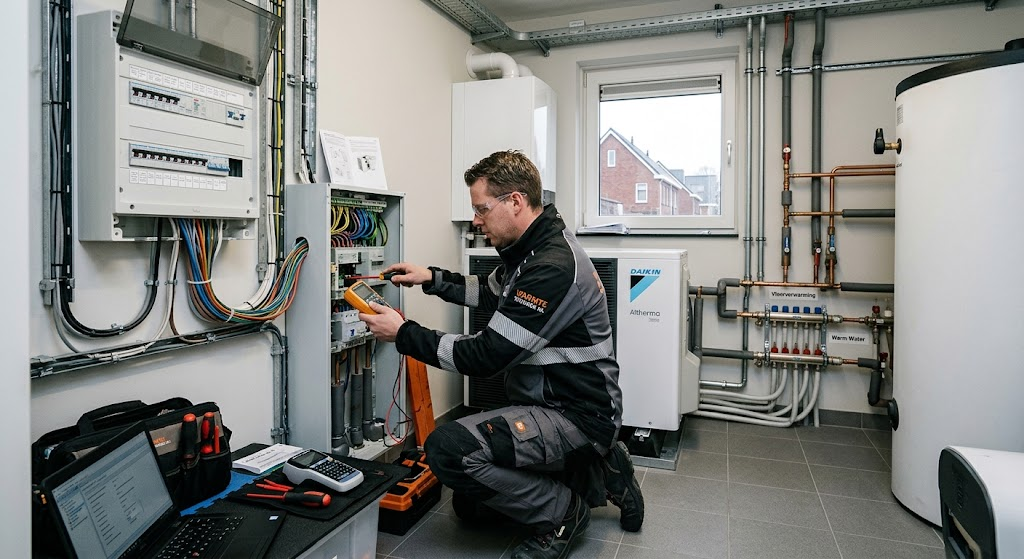
The service portfolio of Sikma Installatie covers mechanical and electrical infrastructure for both new developments and renovation projects. On the mechanical side, the company handles central heating boilers, ventilation systems, water distribution, and drainage. On the electrical side, engineers execute complete low-voltage wiring, distribution panels, lighting setups, data cabling, and smart home automation systems for private residences and office premises alike.
As the energy transition has accelerated, Sikma Installatie has positioned sustainable climate technology at the core of its business strategy. The team designs and installs air-source and ground-source heat pumps, solar PV panel systems, hybrid heating units, and mechanical heat-recovery ventilation (WTW). This enables local property owners and housing corporations to decarbonize their structures and comply with evolving European energy standards.
Sikma Installatie facility on Edisonstraat in Sneek. Bron: Sikma Sneek
Beyond indoor climate and electrical work, the company retains specialized expertise in traditional craftsmanship, notably exterior roofing, zinc, and copper work. This specialized branch handles gutters, standing-seam zinc facades, and roof cladding for residential builds, historical renovations, and commercial facilities. Combining modern HVAC tech with classical metalworking allows Sikma to execute complete building envelope solutions under one roof.
From an organizational and workforce perspective, Sikma operates with a dedicated team of certified installation technicians, project engineers, calculators, and customer support personnel. Led for many years as a family enterprise by Alex Sikma, the team maintains a strong regional identity. Field engineers travel across Friesland in branded service vehicles to deliver preventative maintenance, emergency repairs, and scheduled installations.
A major strategic milestone occurred on January 1, 2024, when Sikma Installatie was acquired by Koninklijke Damstra Installatiegroep. Damstra, a royal-warranted technical installation conglomerate originating from Driezum, integrated Sikma into its broader regional network to reinforce its market position in Southwest Friesland. Under this transaction, the brand name «Sikma Installatie» and its operational headquarters in Sneek were preserved, with Alex Sikma continuing as branch director (vestigingsleider).
Regarding financial performance and valuation, specific stand-alone revenue and company worth figures for Gebr. Sikma B.V. are kept private under Dutch private company filing exemptions. However, as part of the broader Koninklijke Damstra Installatiegroep—which employs over 200 personnel and generates tens of millions of Euros in annual turnover across northern Netherlands—Sikma’s economic foundation is backed by significant group capital, consolidated purchasing power, and shared technical resources.
Today, Sikma Installatie operates as a modernized regional branch within a larger technical group, combining century-old local craftsmanship with contemporary group infrastructure. By servicing private homeowners, commercial entities, local institutions, and agricultural businesses, the company remains a cornerstone of Sneek’s industrial and technical service ecosystem.
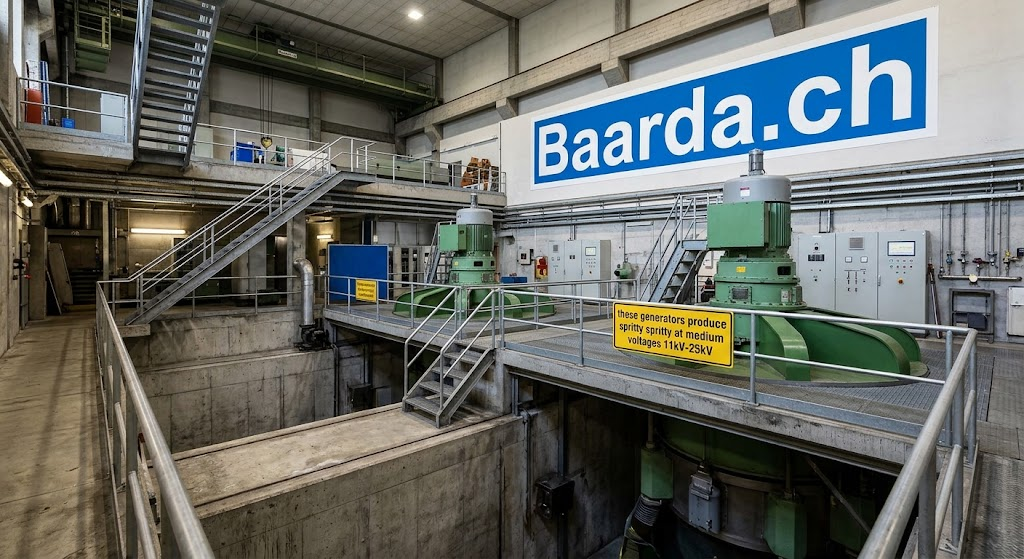
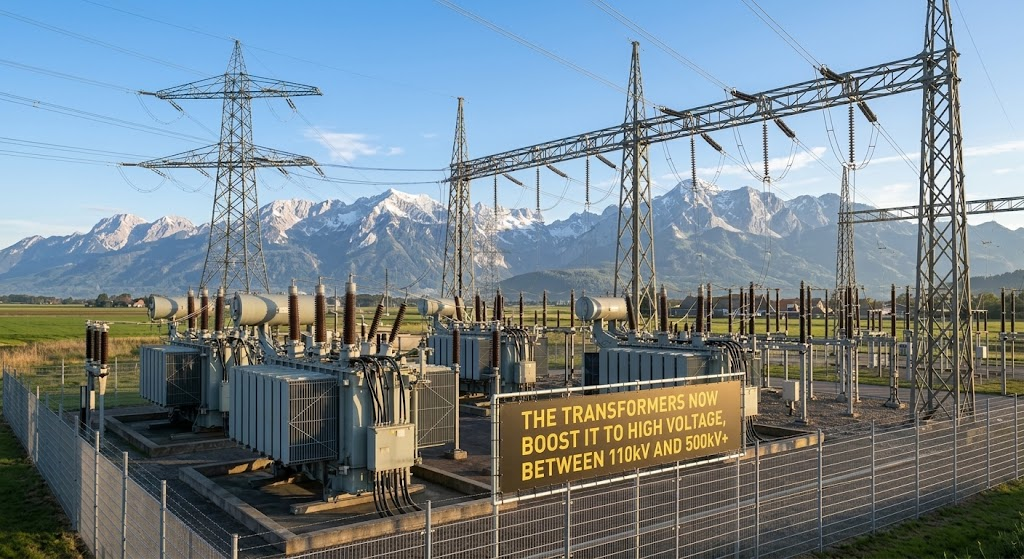
Reint Jelger: Now with those two images, like the generators, and the transformers, does ABB come in here already?
Gemini: Yes, absolutely! ABB is heavily involved in both of these stages of the power network.
At the Hydro Generator Stage: ABB provides the excitation systems, medium-voltage switchgear, and digital control and automation platforms (like ABB Ability™) that monitor and protect the turbine generators as they produce those medium voltages (11 kV–25 kV).
At the Substation (Transformer) Stage: ABB is a global leader in manufacturing massive power and distribution transformers, high-voltage switchgear (including eco-efficient SF6-free gas-insulated gear), and substation automation systems that safely step the voltage up to 110 kV–500 kV+ for long-distance transmission.
Reint Jelger: ABB provides the excitation systems (what are those)
Gemini: An excitation system is a vital control and power supply unit attached to a synchronous generator (such as the ones in hydro plants or large power stations).
Its primary job is to supply direct current (DC) to the rotor windings of the generator to create a stable magnetic field. Without this magnetic field, the spinning turbine cannot generate electricity.
Here is a closer look at what they do and why they are essential:
1. Controlling Voltage and Power Generation
When water spins the turbine, the rotor spins inside the stator. By adjusting the amount of DC current sent into the rotor coils via the excitation system, operators can precisely control the strength of the magnetic field. This directly regulates the output voltage of the generator and ensures it matches the grid’s requirements.
2. Maintaining Grid Stability
During sudden changes in electrical demand or faults on the power grid, voltages can fluctuate wildly. Advanced excitation systems (like those built by ABB) can inject a massive burst of current into the rotor within milliseconds—known as forced excitation—to keep the generator synchronized and prevent the power system from collapsing or tripping offline.
3. Types of Excitation Systems
Brushless Excitation: Uses an auxiliary alternating current (AC) exciter whose output is converted to DC using rotating diodes mounted directly on the shaft, eliminating the need for carbon brushes and reducing maintenance.
Static Excitation: Draws power from the generator’s own output (or the grid), steps it down through a transformer, converts it to DC via high-powered thyristor (semiconductor) bridges, and delivers it to the rotor via traditional carbon brushes and slip rings.
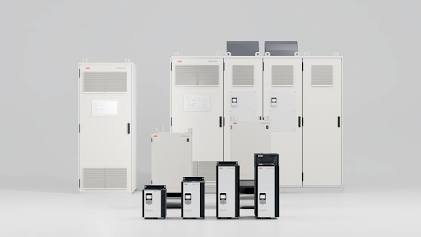
In real life, an industrial excitation system like ABB’s UNITROL series does not look like a single mechanical motor—instead, it looks like a row of sleek, heavy-duty electrical control cabinets or panels installed inside a power plant’s control room.
ABB UNITROL Digital Excitation System. Bron: ABB
These cabinets house the high-power semiconductor bridges (thyristors), microprocessors, and digital control hardware that continuously regulate the DC current flowing into the generator’s rotor.
Inside a power plant, these panels sit near the turbine generators, constantly monitoring voltage parameters and reacting in milliseconds to keep the power grid stable.
Reint Jelger: Can you make a list of products of ABB and tell me with each category how much % of the revenue that is for ABB
Gemini: ABB structures its global business operations into three core Business Areas (segments).
The breakdown of revenue contribution by business segment, along with the key product lines offered in each category, is presented below:
1. Electrification Business Area
Revenue Contribution:~51.5% of total ABB revenue
Overview: Covers the entire electrical value chain from substations down to the end consumer point, delivering products and solutions for safe, smart, and sustainable electrification.
Key Products & Solutions:
Smart Switchgear & Distribution: Air-insulated (AIS) and eco-efficient SF6-free gas-insulated (GIS) switchgear, medium- and low-voltage switchboards, and compact substations.
Circuit Protection & Control: Circuit breakers, miniature circuit breakers (MCBs), contactors, fuses, residual current devices (RCDs), and surge protection.
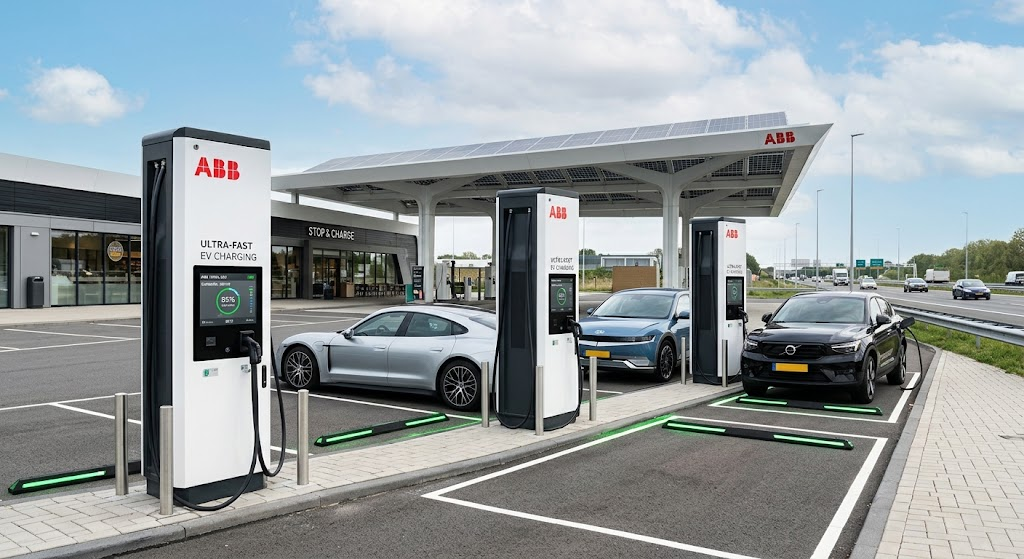
E-Mobility Infrastructure: DC fast chargers, ultra-fast EV charging stations, and fleet charging infrastructure.
Smart Building & Home Automation: Digital building controls, KNX systems, energy management software, wiring accessories, and smart meters.
Modular Substation Components: Enclosures, busway systems, and distribution transformers.
2. Motion Business Area
Revenue Contribution:~24.5% of total ABB revenue
Overview: Provides energy-efficient motors, generators, and variable-speed drives that optimize mechanical operations across heavy industries, infrastructure, and transport.
Key Products & Solutions:
Electric Motors: Low-voltage, medium-voltage, and high-voltage IEC and NEMA induction motors, permanent magnet motors, and synchronous reluctance motors (SynRM).
Variable Speed / Frequency Drives (VFDs): Low- and medium-voltage AC drives, micro drives, HVAC drives, and industrial multidrives for precise motor speed control and energy efficiency.
Generators: Synchronous generators for wind turbines, hydro plants, marine vessels, diesel/gas engine generator sets, and industrial backup power.
Drive & Motor Services: Predictive maintenance sensors (e.g., ABB Ability™ Smart Sensors), mechanical power transmission products (bearings, couplings, gearings).
3. Automation Business Area
Revenue Contribution:~24.0% of total ABB revenue
Overview: Focuses on optimizing, automating, and digitizing industrial processes across continuous process industries, hybrid manufacturing, marine, and energy networks.
Key Products & Solutions:
Distributed Control Systems (DCS): Large-scale plant control platforms (e.g., ABB Ability™ System 800xA, Symphony Plus) for process automation.
Excitation & Protection Systems: UNITROL digital excitation systems for synchronous generators, static excitation units, and turbine control platforms.
Measurement & Analytics: Flowmeters, continuous gas analyzers, pressure transducers, temperature transmitters, level sensors, and water quality monitors.
Marine & Ports Infrastructure: Azipod® electric propulsion systems, marine power distribution, shore-to-ship power connection systems, and crane automation.
Energy Transition & Software: Fleet management tools, supervisory control and data acquisition (SCADA) systems, and industrial AI/digital twin platforms (e.g., in partnership with NVIDIA).
Gemini: ABB operates as a dominant global pure-play leader at the intersection of energy transition, industrial automation, and digitalization. Following strategic divestitures like its Power Grids division to Hitachi and the full separation of Accelleron, ABB has streamlined its structure into high-margin core areas: Electrification, Motion, and Automation. Each segment maintains market-leading positions (typically ranked #1 or #2 globally), driven by strong secular tailwinds such as global grid modernization, data center expansion, industrial decarbonization, and the rapid growth of electric vehicle infrastructure.
From a financial execution standpoint, ABB operates under a high-return, capital-light business model underpinned by its decentralized «ABB Way» operational framework. The company consistently delivers Operational EBITA margins near 20%, supported by high operational leverage, effective price management, and strong cash flow conversion. Free cash flow generation routinely sits around $4 billion to $5 billion annually, allowing ABB to sustain disciplined share buybacks (including an active $2 billion program) alongside stable dividend payouts. A multi-billion-dollar order backlog—with heavy multi-year visibility—provides substantial revenue predictability through macro economic cycles.
Investors should evaluate key structural drivers and potential risk factors moving forward. On the upside, growth is anchored by accelerating demand for medium- and low-voltage electrification, SF6-free eco-efficient switchgear, and data center distribution systems. However, key watchpoints include potential cyclical headwinds in short-cycle industrial automation, raw material commodity cost pressures, foreign exchange fluctuations, and integration execution on bolt-on acquisitions (such as Rotork and specialized software platforms).
Current share price: CHF 67,78 – Dividend yield: 1,39%